


 Newsletter
 Search
India’s Aviation Slowdown: Costly Fuel, Weak Rupee and Falling Demand Squeeze Airlines
- The Core Report
- Published on 21 Nov 2026 6:00 AM IST
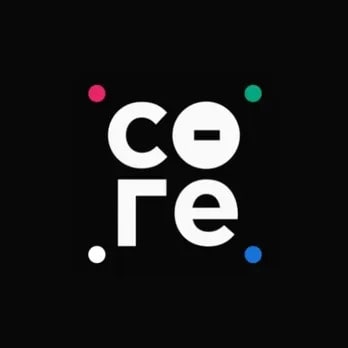
Kinjal Shah, Senior Vice President and Co-Head, Corporate Ratings, ICRA Limited and Amit Mittal, Director AeroIntellect Aviation, Aviation Expert discuss about how with domestic traffic down over 2%, international travel down 18% and ICRA projecting FY27 losses of up to ₹380 billion, airlines need cheaper fuel, easing inflation and lower financing costs to recover.
The Gist
The Indian aviation sector is facing significant challenges due to rising ticket prices and decreased domestic traffic.
- The ongoing conflict in West Asia has escalated oil prices, impacting airline costs.
- Airlines are struggling with reduced flight availability and increased operational costs, leading to financial losses.
Hi and welcome to the Core Report Special Edition. We are focussing on aviation today. As we know, ticket prices are high, there have been capacity constraints and all of that is putting pressure on India's aviation sector, including in the month of October when domestic traffic fell about 5% for the month and that brought the calendar year to date traffic down by about 1.4%.
So, the numbers may not appear large, but remember that this was one of the hottest aviation markets in the world and obviously any slowdown is of some concern. Now, there are very good reasons for all of this beginning and ending mostly with the war in West Asia, which has driven up prices, which has also led to security concerns, including for airlines that have held back their flights. So that's on one end, but as we look ahead, the problem seems to continue for the month of November, for instance, according to Sirium data, there are almost 7,000 fewer domestic flights or 115 fewer flights per day for the next two months, which is usually the peak season when all of us travel for holidays, for weddings and so on.
So the larger question which I'll come to with my guests is, what is the exact nature of the problem? How much of it is distributed? For example, are some airlines facing a bigger problem than others, which they clearly are?
The second and more important point is really when could things recover and what will it take to recover, assuming, let's say, matters improve in terms of oil prices, West Asia security and so on. So to do all of that, I'm joined by Kinjal Shah, Senior Vice President and Co-Group Head of Corporate Ratings at rating agency ICRA and also Amit Mittal, Aviation Expert of Puero Intellect Aviation. Thank you both for joining me.
So Kinjal, let me start with you. So can I get a broad overview from you on where things are right now from your vantage point?
Kinjal Shah: Yeah. So you've given the right context and we're also seeing a significant slowdown in the overall passenger traffic, both domestic and international. So to give you some numbers for the seven months, April to October of the current year, we've seen more than a 2% decline in the domestic air passenger traffic.
And for the international air passenger traffic, the decline has been around 18% plus. So a couple of reasons, obviously, while the main reason that can be attributed to this is the ongoing West Asia conflict, but how does that really impact this domestic air passenger traffic? One, obviously, the cost escalations of oil, which means that the ATF price, we've seen that increase by roughly around 30% of ITD.
So ATF is the single largest cost for the airlines, which used to account for around 30 to 40% of their total cost. And now, obviously, post this increase in the cost, we've seen that rise further to around 40 to 50% of the total cost. So that 30% increase in the cost is quite sizable.
Obviously, the other cost increases which have happened are also because of the depreciation of the rupee against the INR, so against the USD. So that is, again, because a lot of these airlines have expenses in foreign currency, they have foreign currency debt as well. So that also has a hit on the overall cost.
And to that extent, the airlines are not able to pass it on by way of increase in yields, because as such, it is a discretionary demand, I mean, there is elasticity of demand. So if the fare rises are to factor in the entire cost increase, then obviously demand will be impacted further. They have taken price increases in the current year to the extent of 25-30% odd, which is resulting in this slowdown in overall domestic air passenger traffic that we're seeing.
To add to that, even because of the overall inflationary scenario, we've seen that these discretionary spends are getting curtailed. So that's the reason that we're seeing the overall slowdown in the domestic air passenger traffic as well as the international air passenger traffic because of routes being curtailed. We're seeing that many of these airlines are actually curtailing the routes on these West Asian routes.
There are airspaces which have been closed out. So when you have to travel to the other long haul destinations, you have to take longer routes, etc., which means another increase in cost for the airlines because of more fuel costs. There are more aircraft groundings which are happening because you're not able to fly on certain routes.
Then again, there have been issues in the past that we've seen with respect to the Pratt and Whitney engines. So these are also still ongoing. So our estimate is that as on August 26, around 19-20% of the fleet of the Indian aviation industry was grounded, partly because of these Pratt and Whitney issues which continue.
And second is because there is curtailment of routes internationally and obviously because domestic demand is also not really that great, you're not able to recoup those aircraft on the domestic routes. So all these are added costs to the airlines, which they try to pass on partly to the customers and which again has an impact on the demand. So overall, there is a significant slowdown in the traffic growth in the current year.
Right. And let me come to you and let me pick up on international first. Obviously, the slowdown in international is far more than the slowdown in domestic.
13% from about 5%, this is for October. And I think Kinjal made the same point. Why is that happening?
Amit Mittal: See, in international, what is happening is that one is the overall economic aspect. Obviously, the route closures which have happened and the longer routes the airlines will take because of the closure of the airspace. That is a known aspect.
But the other aspect is the overall economic sentiment. You see domestically also India is growing, but overall you see the world economy, the growth rate in the US, in Europe with the economic social disturbances there, saturation in the growth that is slowing down the economic growth there. So when there's an economic slowdown in the markets where people travel mostly for international destinations and then you see Middle East.
Middle East, traditionally UAE, Saudi Arabia, Qatar. These are the markets where the Indian diaspora, the people who work there, business travel, tourist travel, all that happens. And because of the geopolitical disturbances, those things are impacting the international travel.
And then even if you see the Southeast Asian market. So all this, the combination of geopolitical factors, economic factors and the factors in the host countries where the people used to travel, those are affecting the international travel.
Right. And Kinjal, if I can go on to the consequences or the fallout of this. So we've described the reasons why we are seeing what we are seeing, including, let's say, problems on availability of engine parts, which you mentioned.
So like I said, we were the hottest growing aviation market in the world for reasons maybe mostly external. That's not the case now. What is the outcome of this?
What happens when a market like this, where obviously investments are going in because of the promise, suddenly slows down?
Kinjal Shah: Yeah, I think the outcome is one, obviously, like I was mentioning, the air passenger traffic has been impacted. Now, because of that, the financials of airlines also get impacted. So the losses for airlines increase, they already have the debt burden because of the aircraft that they continue to purchase.
And they, at least because of the expectation that the demand will pick up in the near to medium term, the new aircraft orders which have already been given, they continue to take the deliveries of those aircraft. So overall, the airlines continue to have a lot of fixed costs, employees, the other costs like the airport charges, etc. And also with that fixed cost and with the demand not being up to the mark, obviously, the airlines are then incurring more and more losses.
So our estimate also suggests that the losses for FI27 are going to shoot sharply to around 360 to 380 billion rupees for the Indian aviation industry. So now in this current context, I think what is important is how the airlines manage their liquidity? Because one, we know that there are going to be losses.
So while you were lightly mentioning that some airlines may be able to withstand this because of the on balance sheet liquidity that they may have, or some would have, say, parent support or some may not really have those kinds of liquidity available. So there we've seen that at least some support has come from the government in terms of the ECGLS scheme, where the airlines have been availing this liquidity support. Also, we've seen that some support is coming by way of reduction in VAT rates on ATF by certain states.
So some kind of support has started coming in. One needs to see how the demand picks up. And then finally, I mean, demand pickup is going to be the first major thing for the airlines to come out of this entire issue.
And the second is the metric we typically track on the aviation side, which is the RASK, CSK spread, that is the revenue per available seat kilometre and cost per available seat kilometre. So if the costs are increasing, are they able to commensurately pass that increase in the cost on by way of increase in fares while not impacting the overall passenger demand? That is going to be the key to the overall improvement in their financials as well.
Right. And I'll come to the demand side in a moment. Amit, broadly again, when we've been investing in growth and now obviously things have not moved to the extent that we expected or at least thought they would, what changes?
Amit Mittal: In my opinion, Indian aviation is more affected by the lease rate factor rather than the outright cost of financing, because around 85 percent of the fleet of Indian airlines are leased aircraft. And typically what happens is that when the exchange rate of rupee versus USD is going down, even a one rupee decline or 50 percent decline, typically a Boeing 737 or a 320 lease is around 400,000 on a dry operating lease and then there's a maintenance reserve. So even a one rupee change makes it straightaway four lakh rupees of additional cost to the airline.
And multiply that with the 850 aircraft we have got in India, that's a huge number which is a huge impact on the airlines in India. So the long term solution for that could be that one is we have a lower cost of capital so that the companies in gift city are able to foray into the commercial aircraft leasing. As of now, what is happening is most of the commercial aircraft leasing is still happening from outside India, from Ireland, Singapore or Hong Kong and other places.
The people in gift city or the companies in gift city, except a couple of airline leasing companies which have primarily been doing finance leases, operating leases are still being done for the smaller aircraft there. So one is the Indian banks need to come forward on financing of the aircraft. Second is the cost of capital of financing of this aircraft.
And third is some way or some mechanism could be worked out, especially for smaller aircraft, for rupee financing of those aircraft. Because that is the next growth engine which the airlines will need to look at, apart from the domestic and the international level.
Right. And Kinjal, that's a good point to pick up on, because what Amit is saying is that really at this point, not knowing when things will fully recover, we have to manage the cost of capital and the cost of finance that is already embedded in the aircraft that have been brought into this country. So what are the options there from your viewpoint?
Kinjal Shah: Yes, as Mr. Mittal mentioned, right now we're seeing that a large part of the fleet of the Indian aviation industry is on a lease basis. So what typically we've seen is that to manage the overall funding, what airlines have been doing is that they're entering into these sale and leaseback transactions. And when they're doing that, I think they're also gaining from that.
So the cost, because they're placing large orders with the aircraft OEMs, they're getting it at a cheaper rate. And then when they do the sale and leaseback transactions, as and when the deliveries come in, they gain or earn something on those aircraft deliveries as well. So that's been one funding source or liquidity source that these airlines are having.
But that said, I mean, obviously, when they go for these leased aircraft as well, there will be these fixed costs of EMIs, as in the rentals that they will have to continue to bear. And I think the payments can be withstood only when you have that demand coming in. Till then, obviously, that cost will continue to hit these airlines.
So the other way of financing, I think we've also seen the lenders, etc., financing. I mean, in the past, the airlines that had capital were also trying to own the aircraft. But obviously now because of the funding constraints at the airlines themselves, they're not able to own the aircraft.
But many of the aircraft are still going for debt funded ownership as well. But that all means that you're relying more on debt, which means that it's only going to increase the interest or financing cost for them. So like Amit Mittal was mentioning, there have to be some avenues coming in under the Gift City which could probably help the airlines fund their aircraft purchases in a more cost effective manner.
Right. So what happens to the cost that's already there? As in, are airlines able to churn their loans?
Because clearly, as we've agreed, demand is falling, fares are high, but that is not really helping because obviously, I mean, people are not necessarily buying as many tickets at those fares. There is no clear sense that things will improve in the next three months or six months. Or we hope it will improve.
Things are looking better today than they were looking maybe even a month ago, but there is no guarantee. So how do banks, how do airlines work with their banks or the banking system to churn their loans or what are the other options available to them? In a way, I mean, the outcome obviously being that they're physically or from a balance sheet point of view, better positioned or take least damage as we go into recovery.
Amit Mittal: So in my view, what is happening is that banks in India typically have had no exposure to aircraft financing till now. And I've been saying this for a long time because I was head of aviation with Bank of Kolkata and what I've seen is that unless we have got some kind of an aviation structure fund set up in India, which takes care of the financing of the aircraft at the initial stages, let's say a PDP financing, which is around 20 percent of the value of the aircraft, because till the time the aircraft sale and leaseback transactions happen, the airline has to do PDP financing as well. And typically, the delivery period of the aircraft is 18 months to 24 months, depending upon the demand factors and all the supply chain issues. So if the PDP financing is cost effective, that will bring down the cost outlay for the airline.
Second is that the airlines also might need to tweak their fleet, networks and offering of the flights. Maybe as Indigo has been doing, they are consolidating and deploying bigger aircraft in the domestic sectors as well. In Japan, even wide body aircraft fly on domestic sectors and there could be times to come like in the big transports in India, like Delhi, Mumbai, Delhi, Bombay, Mumbai, Bangalore.
There could be a case for a wide body aircraft deployment on the cost estimation and the cost of flying and everything. So these are the methods and ways in which the airlines can reduce their operating cost and try to balance the issues which are not in their control. That is what I would like to say.
Right. OK, let's come to the demand side now. So Kinjal, you mentioned at the outset that demand is a challenge and we again don't know exactly when it will come back.
But if I were to flip that question around, what could bring back demand from your vantage point and what you've seen in previous cycles?
Kinjal Shah: Yeah, so demand for the aviation sector comes from two sources, one is business demand and the other is leisure travel. So obviously leisure travel, I think that has greater demand elasticity than what business travel would have. But in terms of the leisure travel pickup, I think that leisure travel pickup could happen only once we see some rationalisation of the airfare because overall when the economy is in an inflationary scenario, most of the households who would have their budgets in place, they would try to then work along.
And obviously the discretionary spends tend to get cut the most. So I think one, when the inflationary scenario is curtailed, which means that even the airfares are reduced, that's when I think we could see a pickup in the leisure demand. On the business demand, I think it also depends again on how various corporates are doing in terms of their own finances.
So again, because of the inflationary hit on the profits of many sectors that we've seen in the last two quarters, commodity price rises, logistics costs increases and so on. We think that the profits for the overall corporate India have also taken a hit. So when the corporates themselves see a hit on their profits, they would also try to then curtail the discretionary travel.
Wherever there is a travel required, the business travel will happen. But overall, they would also try to see where they can curtail all these expenses. So we'll have to wait and watch until we see the inflationary situation getting rationalised.
That's where I think we will see both the pickup in the business and the leisure demand happening.
Right. And I think inflation is an important point that you've made because we've just crossed six percent consumer price inflation and clearly it looks like it's going to go higher and interest rates are also going to rise. So some of those numbers are not looking very friendly.
But you mentioned that companies are also under strain. Now, when we look at Q2 results, for example, we've had a very strong quarter. But what you seem to be saying is that even if those numbers are good, under those numbers or beneath those numbers, there is a lot of stress.
Kinjal Shah: So that's sector specific, actually. So what we've seen is that revenue growth has happened for the corporate India because obviously the realisations have increased because of the overall raw material costs increasing. But when you look at profits, the profits on a YY basis, many of these sectors have seen a compression because of these raw material cost increases, which cannot immediately be passed on to the customers.
So some sectors like commodity sectors, etc., they have definitely seen an improvement in the profits. But many other sectors, they are seeing some compression in the margins and that pass on of the raw material cost increase will happen with the likes. So we'll start seeing the results in Q3 and Q4.
So if we were to look at the set of circumstances or the combination of circumstances which could bring demand back to aviation specifically, since in many cases, as you said, it's more of a discretionary income. And one is how long could it take for, first of all, demand to come back to normal levels as opposed to the degrowth that we're seeing. And second is for growth to come in the way we saw it, let's say, until last year.
Kinjal Shah: So I think at least FY27 looks to be quite subdued for now. In fact, we had a forecast of the domestic air passenger traffic growing by around 3 to 6 percent in the current year. But maybe there could be a downward bias to that as well, considering that we've already seen a 2 percent plus decline until October.
So FY27 does not seem to be so rosy. FY28, because of the low base of FY27 that we will have, we could probably see some kind of a growth happening there. But again, like I was mentioning, that inflation will be a very important point and one needs to see how the inflationary scenario picks up.
Right. And, you know, one of the things that lead to growth in the market is obviously new routes, new airports. And we've been seeing some of that with some, I would say, mixed success.
So since, Amit, you're back with us, the question really is, we've seen new routes open up, new airports open up. Could those be demand triggers at a time of slowdown, which we are in right now?
Amit Mittal: Yes, so sorry for that interruption. So new routes and new sectors opening up obviously will help in the overall utilisation of the aircraft. But there has to be a certain kind of regional aviation which needs to pick up, because once the regional aviation picks up in a better way, those will act like feeders to the truck routes.
And also when regional aviation picks up, it has a percolating effect on the overall economy. And then more people tend to travel by air. That, in my view, could be one of the factors which could lead to more aviation growth.
Second is that we need to have a certain, one way could be having a VAT on ATF, sorry, GST on ATF, because currently ATF is based on VAT and every state has got its own value added tax on the aviation turbine. If it comes under the purview of GST, then the fuel prices could be kind of normalised across the sectors, across the routes, across the states. And that could help a lot for the aviation industry.
OK, so you're saying in terms of demand trigger, the fare or the cost and therefore the fare itself is the key trigger right now, not anything more?
Amit Mittal: Yes, fare is one of the triggers and second is sometimes there are local disruptions like the closure of the Mumbai airport for renovation, but those are temporary issues. Typically, the airlines need to sort those out with the airport operator, relocate to a separate airport. That impacts the overall growth, particularly on that sector level, it impacts the airlines and the operators because Mumbai is a big airport.
And then the other airports like Jewar airport, those need to pick up, start with the domestic flights, more and more of domestic flights and then add to the international flights so that the overall market expands. Because those are two big airports which have come up in the country in the last, then third is Visakhapatnam, Vizag airport, Goa airport, all these big airports which have come up, Greenfield airports, they need to have more traffic, more flights, more connectivity, so to say, so that the overall market expands.
Right, and I mean, as a resident of Mumbai and somewhere in central Mumbai, I'm only hoping that the move to Navi Mumbai is as delayed as possible because the connectivity is still quite poor. Anyway, Kinjal, I'm coming to you for the last word. So we started out by asking what is going on or what's wrong with aviation today in terms of growth and the potential for growth.
I think we've discussed why that is happening. And we've also talked about what needs to happen or what we need to do to bring some of the demand back, because if demand does not come back quickly, there is going to be economic harm to airlines and of course, by extension, the rest of the aviation industry. As we go, what do you feel that we could do today?
And maybe you want to recap some of the points that you made earlier to make sure that this industry gets all the love it needs.
Kinjal Shah: So one on the demand side, I'm sure, I mean, the demand will pick up, I mean, if not in the near term, in the medium term, I mean, during COVID also when we've seen that the overall travel was closed, but then the pent-up demand which is there, I mean, post pandemic, we did see that pent-up demand coming in. So that pent-up demand will definitely be there. Now one needs to see whether it's happening sooner or later.
That said, I think overall for the Indian aviation industry, what one would require is how the economics work favourably. I mean, how do they control the costs, like I was mentioning earlier, the RASK, CSK spreads that need to improve. So how do the airlines do that in conjunction with the current cost that they already have?
I think that's going to be very important for them to work around.
Got it. We've run out of time. Kinjal Shah and Amit, thank you both for joining me.


