


 Newsletter
 Search
Climate Risk Needs Boardroom Accountability
Nepal’s floods expose a gap in corporate risk management: climate exposure is still treated as a sustainability disclosure exercise, rather than a material business risk with clear ownership, accountability and board-level oversight.
The Gist
On August 26, a glacier broke off in Nepal, resulting in catastrophic floods affecting thousands.
- Over 1,300 fatalities and 84,270 people impacted.
- Infrastructure damage estimated between $4-7 billion, including hydropower projects and bridges.
- Highlights the need for better climate risk management and ownership in corporate governance.
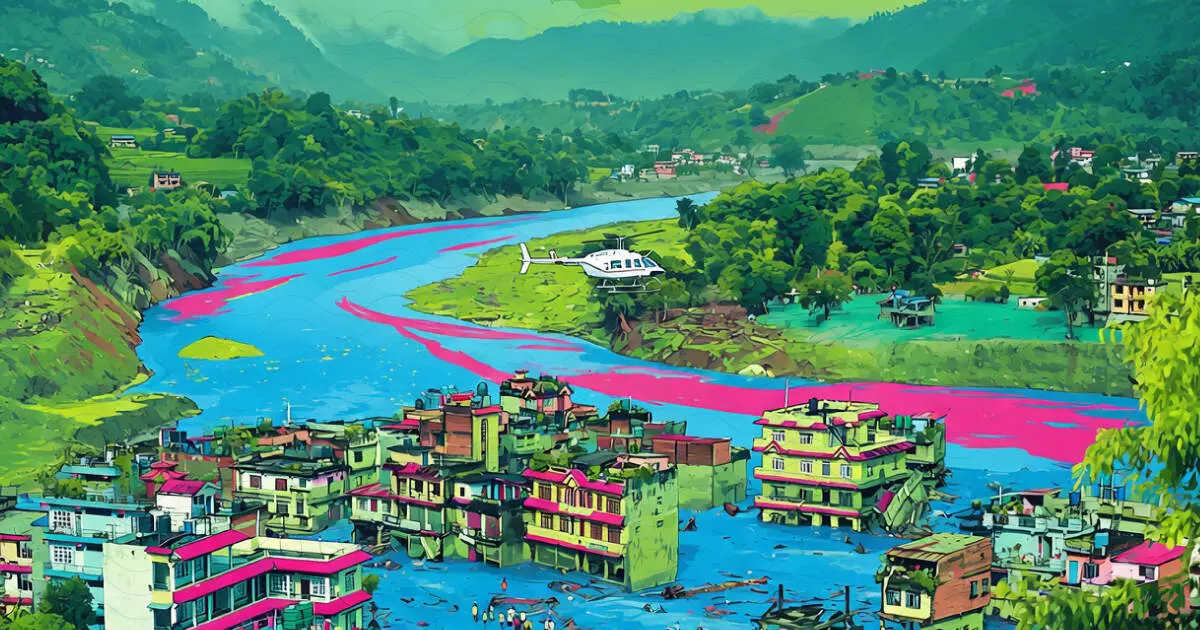
On August 26, a section of a glacier broke off the Langtang Lirung and came down into Nepal's Bhote Koshi river, floodwaters and debris barrelled nearly than 100 kilometres downstream gouging its way into Nepal, Tibet and China. Over 1,300 people are reported dead, at least 84,270 are affected and thousands still missing. Fourteen hydropower and solar projects, 748 megawatts of capacity in total, were wrecked in a single morning, along with 32 bridges and long stretches of road and transmission line. Nepal's government puts the total damage at $4-7 billion.
The aftermath asks a harder question: for the hydropower financiers, insurers, operators and industrial buyers with exposure running through that corridor, who owned this risk? Not who mentioned it in a sustainability report, but rather who had it on the risk register, with an appetite set, an escalation path and someone responsible for acting before it became a disruption.
Climate and nature risk - volatile supply chains, water shortages, resource dependencies - is balance-sheet risk. Good sustainability disclosures are a side effect of doing this well, not the goal itself. And that starts with clear ownership. When any large company is questioned on who owns credit risk, the answer is swift: it is a mandate, a committee, capital set aside, a clear line to the board once exposure crosses a defined threshold. Market risk works the same way, as does operational risk. However, climate risk almost never gets that treatment. It tends to sit with a sustainability team that can produce an efficient report but lacks the authority to set risk appetite, allocate capital or push back on a supply chain operation or a supplier. It appears in the annual disclosures, rather than on the risk committee's agenda. This gap must be read as a structural gap, and not just a resourcing issue.
Nepal is a stark illustration. One glacial event wiped out roughly a tenth of the country's power-generation capacity overnight, along with infrastructure that businesses across two countries depend on. If the same shock would have hit credit markets, exposed institutions would likely have a stress scenario, a defined risk appetite and someone accountable when exposure crossed a threshold. Yet it is more the exception than the norm to see that same rigor applied to the risk of a major flood event disrupting operations, suppliers or financed assets along that corridor.
These urgencies don’t necessarily call for a new department. Enterprise risk management already exists for this purpose, its job being identifying and responding to threats to a company's strategy, operations and financial performance, wherever they come from. Climate risk belongs inside that existing discipline, held to the same standard as other material risks, rather than pushed into a separate reporting track.
In such a scenario, what would real ownership look like? A named owner at board or executive-committee level, with the authority to act, a defined risk appetite so there is an answer to how much physical, or transition risk are we willing to carry. It crucially could also look like a scenario analysis that shape decisions before disruptions occur, where disclosures aren’t an afterthought, and an escalation path to people who can and want to act.
Versions of this architecture already exist. For example, the Task Force on Climate-related Financial Disclosures (TCFD) framework, now largely folded into IFRS S2, was built around this exact question on who owns climate risk inside a company and to what extent. While this isn't the only place where these ideas show up, it is useful as evidence that the governance logic has been thought through. Some companies are taking that logic beyond reporting, incorporating climate risk in the boardroom agenda and actively revisiting it with the risk committee. These first movers get lower, more predictable costs and cheaper capital as green financing grows.
At the same time, investors, for their part, have started pricing in the gap. Globally, investors are increasingly pricing physical and transition climate risks into asset valuations, credit ratings, and cost of capital as extreme weather and environmental rules reshape financial markets. It is thus crucial to ask who owns the exposure, how is it being assessed and what happens when the risk exacerbates?
India has a particular stake in this context, given the scale of what's being built. The country is adding substantial new energy and industrial infrastructure at a pace unlikely to slow. Every plant, grid connection and supply agreement signed this decade will carry the risk architecture designed around it from day one or inherit its absence. Building that governance at the outset is far easier than retrofitting it after assets, contracts and dependencies are already in place.
Nepal's floods will disappear from the headlines long before its bridges and power plants are rebuilt. What should outlast the news cycles though is a harder review into every exposed company – by companies, investors and analysts. Until climate exposure has a clear owner and a name attached to it, the way credit and market risk already do, it will continue to be treated as background uncertainty rather than what it is, which is a material business risk that needs to be managed and mitigated before the next inevitable catastrophe.
Core.
Core.


